Available for internships · Stuttgart, Germany
Meet
Babariya
AI engineer. I design the benchmarks frontier AI agents are trained and graded on at Datacurve (YC), and build LLM systems that are measured, not guessed. Former options trader turned quant developer. 2.5 years on a live index-options desk, 12th in Germany at IMC Prosperity, and backtests that account for fills, costs and regimes.
too easy · rejected hard enough · kept Each dot is one frontier-agent run. Lower is harder.
t = 12m p5 71.9 p50 95.7 p95 141.5
- Now
- ML Benchmark Engineer Datacurve · Y Combinator
- Before
- Derivatives Trader Jainam Broking · 2022–24
- Studying
- B.Sc. Business Info. Systems Furtwangen University · 1.55
- Looking for
- Internship / Werkstudent AI · ML · Quant — Germany
01 — Selected work
Case studies with the numbers left in.
- 07 02 Auditing a +557% breakout strategy Quant research · strategy due diligence +78% Sharpe, walk-forward out of sample 2026
- 02 05 Benchmarks agents can't saturate Datacurve (YC) · Project Eris < 0.8 target frontier-agent score 2026
- 01 04 A virtual sensor for EV motor temperature ML + LLM · Automotive virtual sensing 1.50 K² test error · best published 2.87 2026
- 05 06 Financial Filings RAG RAG · grounded QA over SEC filings [n] every claim cited or refused 2026
- 04 01 Validating option models on live BTC data Quant research · model validation 18,555 option-days hedged out of sample 2026
- 03 03 QuantPilot Product · AI copilot × copy trading on Hyperliquid DSR Deflated-Sharpe trader ranking 2026
- 06 07 German Traffic Sign Recognition Computer vision · ADAS perception 97.7% test accuracy, 43 classes 2026
Also on GitHub
- Financial Analyst Agent Hand-written tool-use loop over VaR / vol / Sharpe tools
- Black-Scholes vs Heston Fourier-priced Heston against Black-Scholes; skew from vol-of-vol
- Delta-Hedging Simulator Short call, delta-hedged: gamma vs theta under realized ≠ implied
- GARCH Intraday Strategy Signals from GARCH volatility forecasts
- Portfolio VaR Analyzer Historical, parametric and Monte Carlo VaR
- Credit Risk Modelling PD and expected-loss estimation with ML
- Excel VBA Risk Toolkit OOP VBA: covariance VaR report with auto chart
- Volatility Curve Prediction Iterative imputation with gradient-boosted estimators
02 — Experience
Benchmarks for AI agents. Before that, risk on a trading desk.
- Sep 2026 — now Remote
DatacurveYC
ML Benchmark Engineer · Project Eris
Designing the Kaggle-style challenges Datacurve uses to train and evaluate autonomous AI agents.
- Own each challenge end to end: data sourcing, leak-free split pipeline, evaluator, rubrics and a reference solution.
- 25+ designs across vision fine-tuning, sequence-to-sequence, from-scratch and LLM-evaluation tracks, on licensed real-world data.
- Calibrate difficulty so frontier agents land below 0.8, from ridge floors and fine-tuned CNNs to exact Bayes-optimal decoders.
- Apr 2022 — Dec 2024 Surat, India
Jainam Broking
Derivatives Trader
Two and a half years trading weekly index options on a live desk.
- Traded NIFTY and BANKNIFTY weekly options with delta-neutral structures across expiry cycles.
- Hedged in real time, re-balancing delta and vega as volatility expanded.
- Sized and monitored positions with pricing models and Greeks-based limits.
- Mar 2025 — now Furtwangen, DE
Furtwangen University
B.Sc. International Business Information Systems
Current grade 1.55.
- Self-study: MIT OCW Mathematics with Applications in Finance; WorldQuant University Applied Data Science Lab.
03 — Record
Open leaderboards, thousands of teams.
| Competition | Detail | Result | Percentile |
|---|---|---|---|
| IMC Prosperity 4 | Algorithmic trading · 12th in Germany | 230 / 18,803 | |
| Kaggle — CIBMTR | Silver medal · survival modelling | 120 / 3,325 | |
| Kaggle — MITSUI | Bronze medal · commodity prediction | 165 / 1,711 | |
| WorldQuant BRAIN | WorldQuant Challenge | Gold level | — |
| Kaggle | Competitions Expert | Top 1% | — |
| AlgoTrade Hackathon | Zagreb · options market-making | Competed | — |
04 — About
I trust numbers I can test against reality.
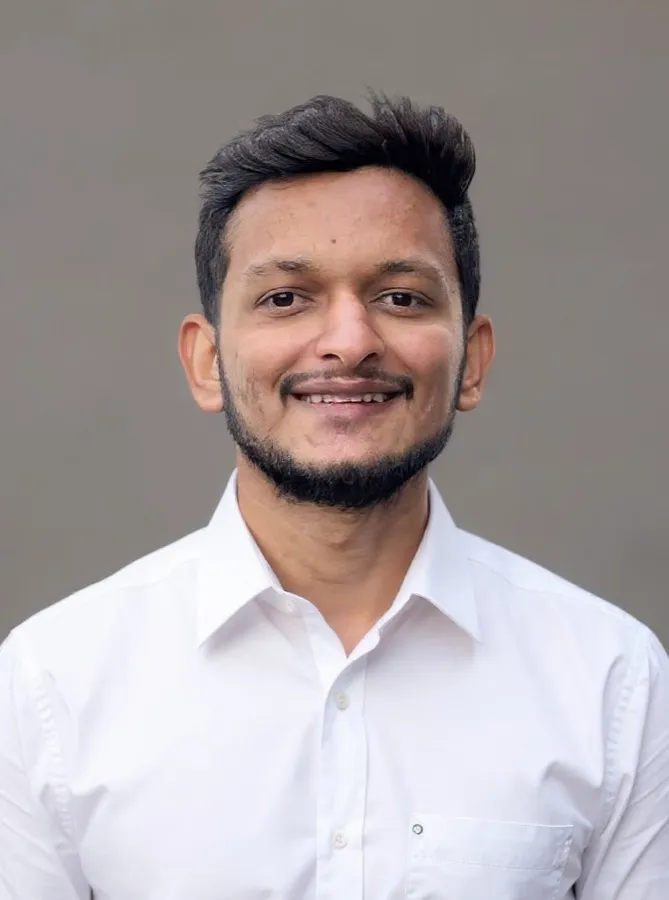
Meet Babariya · Stuttgart
Before moving to Germany to study Business Information Systems, I spent two and a half years trading index options on a live desk. Trading taught me to distrust results that look too good, to model costs, and to ask what changes when the regime changes.
I now apply the same habits to AI. At Datacurve I build the challenges AI agents are evaluated on, which means thinking adversarially about leakage, shortcuts and saturation. On the side I build products end to end, from a Python quant service to a TypeScript front end.
LLM systems
- Claude / OpenAI APIs
- RAG
- Embeddings & vector DBs
- Agents & tool use
- LLM evaluation
- Benchmark design
Machine learning
- PyTorch
- Hugging Face
- Fine-tuning
- Computer vision
- scikit-learn
- Gradient boosting
Quant
- Options & Greeks
- Volatility models
- Monte Carlo
- VaR / CVaR
- Backtesting
- Walk-forward OOS
Engineering
- Python
- TypeScript
- SQL
- Next.js / Astro
- FastAPI
- PostgreSQL
- Docker
- NISM Series-VIII · Equity Derivatives (SEBI)
- NISM Series-XV · Research Analyst (SEBI)
- Applied Data Science Lab · WorldQuant University
- English — fluent · German — A2